Forget the 20% rule. The federal 5% Deposit Scheme, expanded on 1 October 2025, lets eligible first home buyers purchase with as little as 5%. Here's what that looks like in real money — by state, by scheme, by buyer type.
The deposit myth
Most Australians believe they need 20% deposit to buy a home. For a $700,000 property, that would be $140,000. The Australian median full-time wage is about $100,000 — saving $140,000 from a single income takes 7–10 years.
The 20% deposit rule is one of the most expensive myths in Australian personal finance. It has kept a generation of renters in the rental market when they could have been owners.
5%That's all most eligible first home buyers actually need in 2026, under the expanded federal 5% Deposit Scheme. For a $700,000 home: $35,000, not $140,000.
The minimum deposit, by buyer type (2026)
| Buyer type | Minimum deposit | Scheme | LMI waived? |
|---|---|---|---|
| Standard first home buyer | 5% | 5% Deposit Scheme | Yes |
| Single parent or guardian | 2% | Family Home Guarantee | Yes |
| Buyer under income caps | 2% | Help to Buy (government co-owns up to 40%) | Yes |
| WA buyer | 2% | Keystart | Yes |
| SA buyer | 2–3% | HomeStart | Yes |
| Standard buyer, no scheme | 5–10% | Conventional loan | No (unless 20%+) |
| Standard buyer, 20%+ saved | 20%+ | Conventional loan | N/A (no LMI needed) |
Each row tells a different story about how much deposit you need. The schemes that waive LMI are the most generous, because they're the difference between paying $25,000 extra (the LMI premium on a 5% deposit) and paying nothing.
What "deposit" actually includes
Your deposit is the cash you put into the purchase at exchange. But the cash you need to settle is larger than just the deposit. The full upfront cash stack is:
- Deposit (5–10% of price) — paid at exchange. The headline number most people focus on.
- Stamp duty — paid at settlement. Often $0 for first home buyers under state thresholds, but can be $10K–$30K for established homes above the threshold.
- Conveyancing fees — $800–$2,500 + disbursements.
- Building & pest inspection — $400–$800.
- Loan establishment fee — $0–$1,500.
- Mortgage registration fee — $150–$300.
- Removalists — $800–$2,500.
- Insurance setup — $100–$500.
- Connection fees — $100–$300.
- Buffer — $2,000–$5,000 minimum.
Subtract any FHOG (paid at settlement as a deduction from the deposit). Then divide by the price to see your real deposit ratio.
For a $700,000 NSW home with $35,000 cash deposit, no LMI (under the 5% scheme), $0 stamp duty (FHB exemption), and a $5,000 FHOG (eligible for new home only, so not in this case)...
Total cash at settlement: $42,000–$48,000. That's roughly 6–7% of the price, not 5%. Still way better than 20%.
What the 5% Deposit Scheme actually does
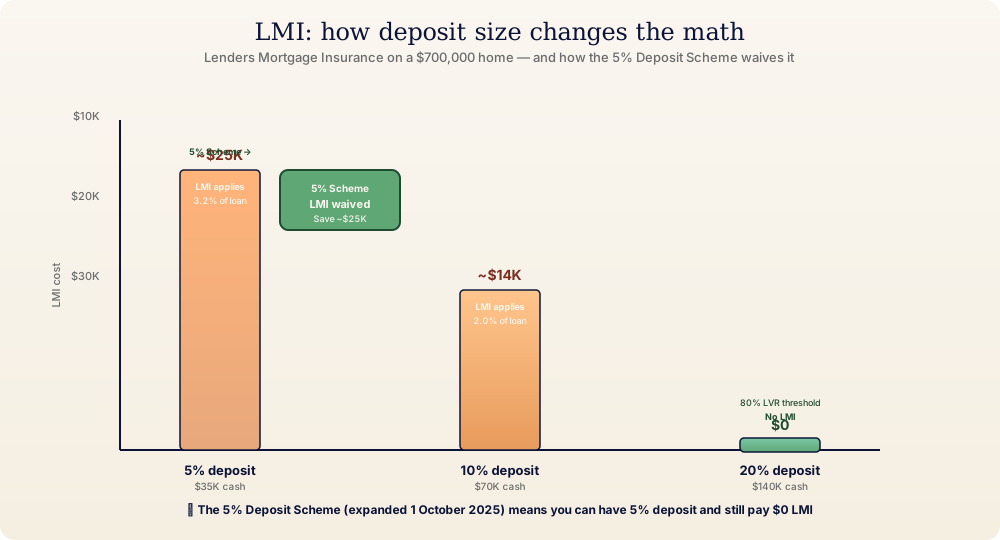
The federal 5% Deposit Scheme (formerly First Home Guarantee) lets you buy with 5% deposit and no Lenders Mortgage Insurance. The Government guarantees the next 15% of the property value to participating lenders.
From 1 October 2025, the scheme was expanded: no income cap, uncapped annual places, and price caps were raised or removed for most states. Property price caps by state:
- NSW: $1,500,000 (Sydney, Newcastle, Wollongong and most regional centres)
- VIC: $950,000 (Melbourne and regional centres) / $650,000 (regional VIC)
- QLD: $1,000,000 (Brisbane, Gold Coast, Sunshine Coast) / $700,000 (regional QLD)
- WA: $850,000 (Perth metro) / $600,000 (regional WA)
- SA: $900,000 (Adelaide) / $500,000 (rest of SA)
- TAS: $700,000 (metro) / $550,000 (regional)
- ACT: $1,000,000
- NT: $600,000
Source: Housing Australia
What about the Family Home Guarantee?
The Family Home Guarantee is for single parents or guardians with at least one dependent child. The Government guarantees 18% of the property value to the lender. The minimum deposit is 2%, and LMI is waived.
You don't have to be a first home buyer — you just can't currently own property. So a single mum who's been renting for years after a separation can buy a home for her family with 2% deposit.
The 2025 expansion removed the place cap and lifted most property price caps. Places are limited annually, so apply early in the financial year.
What about Help to Buy?
Help to Buy is the most generous scheme for buyers under the income caps. The Government co-owns up to 40% of the price of a new home, or 30% of an existing home. You save 2% deposit. The Government's share comes out of your sale proceeds when you sell (or earlier, if you choose to "staircase out" by buying back the equity).
Income caps: $103,000 single, $165,000 couple or single parent. Property price caps vary by state (NSW up to $1.3M, NT down to $600K).
The catch: when you sell, the Government gets its share of any capital gain. So if your home doubles in value, the Government takes 40% of the gain. For most buyers, this is fine — they were going to be renting otherwise.
Help to Buy opened on 5 December 2025. Apply through participating lenders.
Why the 20% deposit rule is wrong
The 20% number came from a real rule: lenders will not charge Lenders Mortgage Insurance if you have 20% deposit. That's all the rule says. It does not say you need 20% to buy a home — it says that if you have 20%, you'll avoid the LMI fee.
The mistake the myth makes: treating the 20% threshold as a minimum instead of an LMI-waiver threshold. Banks never required 20% deposit to lend — they required 20% to lend without insurance. With the federal 5% scheme in place, even the LMI is waived at 5% deposit.
So: the 20% rule was always a "you'll pay LMI if you don't have this much" rule. It's never been a "you can't buy unless you have this much" rule. And since 1 October 2025, it's not even that.
The "genuine savings" rule (and how to satisfy it)
One catch: the 5% Deposit Scheme (and most lenders) require genuine savings. This is typically 3–5% of the property value held in your name for at least 3 months. A one-off deposit from a parent or inheritance may not count — the lender wants to see that you can actually save, not just receive money.
Some tips to satisfy genuine savings:
- Automate weekly or fortnightly transfers into a separate savings account, even small amounts ($50–$100).
- If you've had the deposit for less than 3 months, ask your broker about lenders with more flexible genuine-savings policies.
- Gifted deposits are accepted by most lenders with a statutory declaration from the gift giver — but they don't count as "genuine" for some lenders.
- First Home Super Saver withdrawals count as genuine savings for most lenders.
How to actually build the deposit
For most first home buyers in 2026, the deposit stack is:
- Cash savings — automate transfers. Treat it like a non-negotiable bill.
- First Home Super Saver — make voluntary super contributions, claim the 15% tax rate instead of your marginal rate. Effective saving of $2,000–$3,000 per year for a typical earner.
- State First Home Owner Grant — paid at settlement, so doesn't help you save but reduces the cash you need at settlement.
- Help to Buy — if you qualify, the Government contributes up to 40% of the price, which means you need far less cash.
A common scenario: $25,000 cash savings + $15,000 FHSS + $30,000 QLD FHOG = $70,000 "deposit" stack on a $700,000 home. That's 10% effective, with LMI waived under the 5% scheme. You settle with $40,000 of your own money, plus the FHOG paid at settlement.
Use the calculator to see your specific numbers for your state and price.
The minimum practical deposit, by state
The state-level grant landscape shifts the realistic minimum deposit:
| State | Minimum practical deposit stack (with schemes) |
|---|---|
| NSW | 5% + $10K FHOG if new (otherwise 5% alone) |
| VIC | 5% + $10K FHOG if new (otherwise 5% alone) |
| QLD | 5% + $30K FHOG if new — combined, very low net cash |
| WA | 2% (Keystart) or 5% + $10K FHOG if new |
| SA | 2–3% (HomeStart) or 5% + $15K FHOG if new |
| TAS | 5% + $20K FHOG if new (until 30 June 2027) |
| ACT | 5% (no FHOG, but $0 stamp duty at any price since 1 July 2026) |
| NT | 5% + $50K HomeGrown (until 30 September 2026) |
What this article isn't saying
Lower deposits are not always better. Borrowing more means:
- Larger mortgage, more interest over 30 years
- Higher monthly repayments, less buffer if rates rise
- Less equity in your home if prices fall
For most first home buyers, the choice isn't really "5% or 20%". It's "5% under the scheme and start building equity, or wait 5+ years to save 20% and miss years of ownership". In most markets, the trade-off favours buying sooner with the scheme.
But don't borrow the maximum. Aim for monthly mortgage repayments below 30% of your take-home pay. Stress-test at 7–8% interest. Build a 6-month buffer of living expenses before you commit.
Scheme eligibility, income caps, property price caps and grant amounts change. We verify against Housing Australia and each state revenue office before publishing. Final eligibility is determined by your lender, not by this article.